
Investment Opportunity
Technology & IT
Nepal's young workforce, English proficiency, competitive costs, and government-backed Digital Nepal Framework make it South Asia's next emerging technology hub. IT exports are growing at 20%+ annually.
USD 100M+
Annual IT Exports
15,000+
Tech Graduates Per Year
70%+
Mobile Banking Penetration
200+
Registered IT Companies
Technology by the Numbers
USD 0M+
Annual IT services exports, growing 20%+ per year
0+
Tech graduates annually · median age 24
0 MW
Installed clean power — up to 1,000 MW surplus in monsoon
$0.000/kWh
Wet-season hydropower tariff (Rs 4.80/kWh) — globally competitive
0%
Cheaper cooling than warm-climate locations
0%+
Mobile banking penetration · 200+ registered IT companies
Sources: NTB / NEA / NRB, WorldLink, Kathmandu Post, IEA — refresh quarterly.
The Thesis: Nepal's Digital Decade
Two curves are converging. The first is global: AI is driving one of the largest infrastructure build-outs in modern history — data-center electricity demand exceeds 460 TWh today and could pass 1,000 TWh by 2030, while India's data-center power requirement alone is projected to more than double to 5,000+ MW by 2030. The second is Nepali: the country's hydropower fleet has reached 4,400 MW on its way toward 42,000 MW of economically feasible capacity, and already spills up to 1,000 MW of clean surplus every monsoon for want of demand.
Where those curves cross sits an unusual national opportunity: instead of exporting raw electrons through contested transmission lines, Nepal can convert clean energy into computation — data centers, GPU clusters, cloud services — and export it as bits through fiber. Iceland built this exact model on geothermal; Bhutan is proving it next door with a planned 40–50 MW, ~USD 450M AI data center. Nepal's version adds what neither has: a border with the world's largest emerging digital market on one side and the world's largest manufacturing economy on the other, plus a UTC+5:45 time zone bridging European and East Asian business hours.
Green Data Centers & AI Compute
The Natural Advantages
Stranded clean power
Up to 1,000 MW of monsoon surplus today, with 42,000 MW economically feasible — the single scarcest input in the global AI race is exactly what Nepal over-produces.
Himalayan free cooling
High-altitude ambient temperatures cut cooling costs ~15% versus warm-climate hubs; cooling is typically 30–40% of a data center's power bill, so the climate is a structural margin advantage.
Competitive tariffs
Wet-season hydropower at ~$0.035/kWh rivals the world's cheapest green-compute destinations.
Geography as strategy
Fiber routes to both India and China; latency-relevant proximity to a subcontinent adding hundreds of millions of internet users; a neutral jurisdiction between two digital superpowers for regional data hosting.
The Bhutan proof point
A neighboring Himalayan kingdom is already monetizing surplus hydropower through compute — validating the model at Nepal's doorstep.
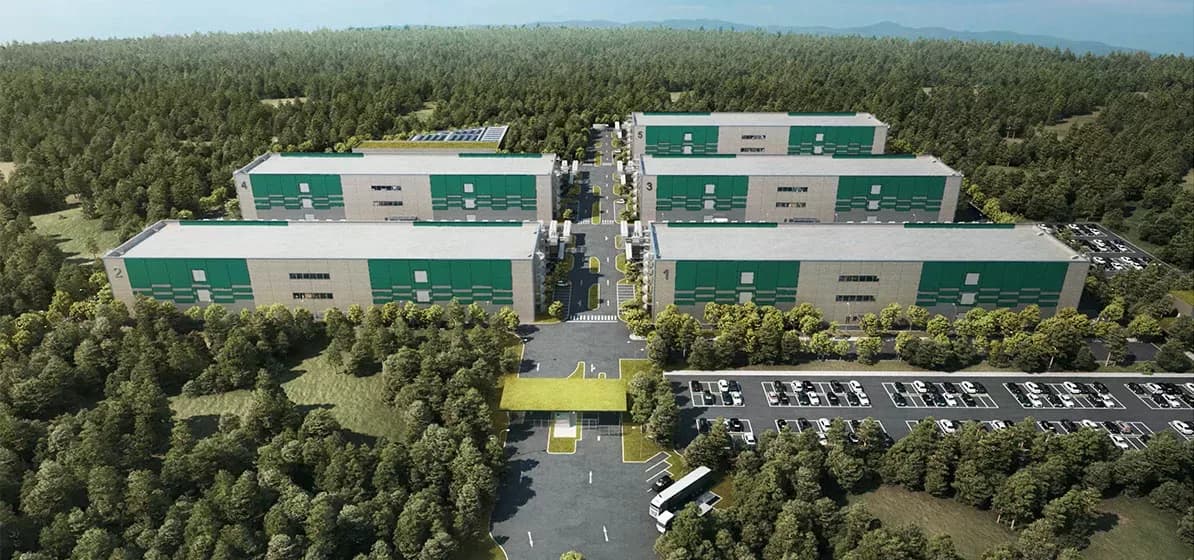
De-Risking the Opportunity
Seismic exposure
Tier-appropriate seismic engineering, site selection outside high-hazard microzones, workload classes (batch AI training) that tolerate failover better than transactional hosting.
Seasonal water variability (winter generation dips)
Hybrid PPAs blending storage-hydro, dry-season solar, and batteries; Phase-1 workloads sized within firm winter capacity.
Connectivity redundancy
Co-invest alongside the Nepal Internet Exchange scale-up and diverse cross-border fiber routes (multiple Indian routes + planned Chinese routes) before Phase-3 scale.
Regulatory maturity
A data-center/cloud policy framework is under active discussion; early entrants shape it. Note: NRB does not recognize cryptocurrency — the credible play here is AI, cloud, and colocation, not coin mining.
Invest in
Software & IT Services Export
USD 100M+ in annual exports growing 20%+ a year, 200+ companies serving US, UK, Australian and Gulf clients, and cost structures 30–60% below Indian equivalents with comparable English. The next leg of growth: moving up the value chain from outsourced development to product companies, AI-augmented services, and dedicated offshore development centers (ODCs) for global firms.
Invest in
Business Process Outsourcing & Global Capability Centers
An English-speaking talent pool at 30–50% below Indian costs, UTC+5:45 overlapping Europe and Asia in a single shift, and strong accounting, legal and design talent. The future-growth angle: not commodity call centers but Global Capability Centers (GCCs) — finance, analytics, legal-process and design hubs for mid-size Western firms priced out of Bangalore and Manila.
Invest in
Fintech & Digital Finance
Mobile banking penetration above 70%, an NRB sandbox framework, digital-wallet regulations in force — and an underserved rural credit market that branch banking will never profitably reach. Growth frontier: digital lending, micro-insurance, remittance-linked financial products for 3M+ Nepalis abroad, and payment infrastructure for the digitizing SME economy.
Invest in
E-Commerce & Logistics Tech
A USD 500M+ domestic e-commerce market still early in its S-curve, with last-mile delivery, address-system innovation, and cold-chain logistics as the picks-and-shovels opportunities. Mountain geography makes logistics tech a necessity, not a luxury — including drone-delivery corridors for high-value, hard-to-reach routes.
Invest in
EdTech & Digital Skills
Six million students, low EdTech penetration, surging demand for English-medium digital learning — and a national interest in scaling the very tech-graduate pipeline (15,000+/year) that every other section of this page depends on. The compounding play: EdTech ventures that train the workforce for the data-center, software, and GCC economy.
Invest in
Technology Infrastructure Projects
Government and private sector investments creating the backbone of Nepal's digital economy — and the physical foundation the Digital Decade thesis is built on.
Hetauda IT & Cyber City
A planned technology township in Hetauda with plug-and-play IT office space, 24/7 power from adjacent hydropower, fibre connectivity, and residential facilities. Targeting software companies, BPO operations, and data centre investors.
Investment Scale
USD 250 Million
The natural Phase-2 data-center campus site — 24/7 adjacent hydropower.
Sunsari Technology & Innovation Park
Eastern Nepal's technology hub, adjacent to the Biratnagar industrial belt. Designed for IT services export, electronics assembly, and technology education institutions. Adjacent to Indian border for talent and market access.
Investment Scale
USD 180 Million
A second growth pole for Phase-2 colocation once Hetauda scales.
Kathmandu IT Park Expansion (Baneswor)
Expansion of Nepal's first IT Park in Baneswor, Kathmandu. The National Information Technology Center (NITC) manages the facility. Phase 2 expansion includes new data centre capacity, cloud infrastructure, and co-working facilities.
Investment Scale
USD 120 Million
Already adding data-centre capacity — the capital's Phase-1 edge-compute anchor.
Digital Nepal Framework Implementation
The Government of Nepal's comprehensive digital transformation programme across 8 digital domains: digital foundation, digital government, digital economy, digital agriculture, digital health, digital education, digital tourism, and digital financial services — all open to private investment.
Investment Scale
USD 500 Million
The government-as-customer demand base that Phase-1 edge data centers are built to serve.
Nepal Internet Exchange (NIXP) Scale-up
Upgrading Nepal's internet exchange infrastructure to reduce bandwidth costs, improve latency, and enable cloud and CDN services. Investors in backbone connectivity infrastructure are actively sought.
Investment Scale
USD 40 Million
The connectivity backbone Phase-3 compute export depends on.
Fintech & Digital Payments Hub
Nepal Rastra Bank has issued fintech sandbox licences and digital wallet regulations. Mobile banking penetration at 70%+ creates a platform for digital lending, insurance, and payment fintech ventures requiring seed and growth capital.
Investment Scale
USD 100 Million
The digital-payments rail every other vertical on this page ultimately settles through.
Why Global Investors Are Watching
Talent
Median age 24, 15,000+ tech graduates/yr, costs 30–60% below India.
Time Zone
UTC+5:45 bridges European and Asian working hours.
Power
Clean, cheap, and increasingly abundant — the AI era's scarcest input.
Climate
Himalayan cooling as a structural cost advantage.
Policy
Digital Nepal Framework (~USD 500M), SEZ/IT-park tax holidays, no FDI minimum for ICT via the Automatic Route.
Diaspora
3M+ Nepalis abroad, from Silicon Valley to Singapore — deal flow, capital, and returning talent.